CALGARY, AB, Nov. 8, 2026 /PRNewswire/ -- Strathcona Resources Ltd. ("Strathcona") (TSX: SCR) and Greenfire Resources Ltd. ("Greenfire") (TSX: GFR, NYSE: GFR) today announced a definitive agreement (the "Arrangement Agreement") for Strathcona to acquire all of the outstanding shares of Greenfire (the "Transaction").
Transaction Structure
Under the terms of the Arrangement Agreement, Greenfire shareholders may elect to receive, at their election, either:
- 0.25 shares of Strathcona for each share of Greenfire (the "GFR Share Option"), equating to $9.09 per Greenfire share or a 15% premium to Greenfire's closing share price on November 6, 2026 based on Strathcona's closing price on the same day, or;
- $11.00 in cash per Greenfire share (the "GFR Cash Option"), equating to a 39% premium to Greenfire's closing share price on November 6, 2026, or a 26% premium to Greenfire's trailing 30-day volume-weighted-average price.
Neither the GFR Share Option nor the GFR Cash Option will be subject to proration, allowing all Greenfire shareholders to receive their election in full. Waterous Energy Fund (together with its affiliated funds, "WEF"), the current holder of 72% of Greenfire's outstanding shares and 57% of Strathcona's outstanding shares, has signed a support agreement in favour of the Transaction under which it will elect to receive the GFR Share Option for its Greenfire shares.
Depending on the elections made by non-WEF Greenfire shareholders, Strathcona expects to issue between approximately 43 million and 60 million Strathcona shares to Greenfire shareholders (equating to 17% to 22% of the pro forma business) and pay cash consideration of up to approximately $740 million. Inclusive of Greenfire's approximately $550 million of net debt(1) outstanding as of September 30, 2026, this equates to a total transaction value of approximately $2.7 to $2.9 billion(2), based on Strathcona's closing share price as of November 6, 2026.
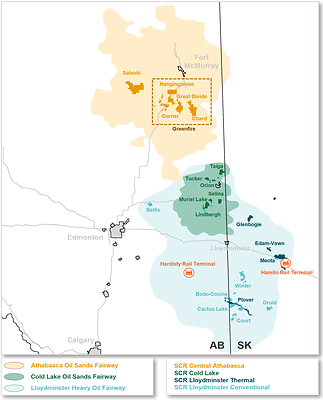
Strathcona expects the existing Greenfire leadership team to continue to lead day-to-day operations of Greenfire's assets within a new Strathcona business unit – SCR Central Athabasca – with Colin Germaniuk, President of Greenfire, serving as President of SCR Central Athabasca. Like Strathcona's three existing business units (SCR Cold Lake, SCR Lloydminster Thermal and SCR Lloydminster Conventional) SCR Central Athabasca will function semi-autonomously within Strathcona, to maximize accountability and operational performance.
The following table sets forth selected capitalization, production and reserves information for each of Strathcona and Greenfire and for the combined business following completion of the Transaction.
Strathcona | Greenfire | Pro Forma Strathcona | |
Capitalization(4) | |||
Share Price (C$ / share) | $36.34 | $9.09 – $11.00 | $36.34 |
Shares Outstanding (mm) | 214.2 | 240.4 | 274.3 – 257.5(2) |
Market Capitalization (C$bn) | $7.8 | $2.2 – $2.6 | $10.0 – $9.4 |
Net Debt (C$bn)(1) | $1.7 | $0.5 | $2.3 – $3.0 |
Total Enterprise Value (C$bn) | $9.5 | $2.7 – $3.2 ($2.7 – $2.9 incl. WEF GFR | $12.2 – $12.4 |
Production | |||
YTD 2026 Production | 119 Mbbls / d | 34 Mbbls / d(3) | 153 Mbbls / d |
TEV / bbls / d | $80,000 | $80,000 - $84,000(2) | $80,000 |
2031E Production | 200 Mbbls / d | 60 Mbbls / d | 260 Mbbls / d |
TEV / bbls / d | $47,000 | $46,000 - $48,000(2) | $47,000 |
Reserves | |||
2P Reserves | 2,166 MMbbls | 850 MMbbls | 3,016 MMbbls |
Reserves Life Index | 50 Years | 68 Years | 54 Years |
YE 2025 2P PV-10, After-Tax (excl. synergies) | $12,692 | $3,745 | $16,437 |
TEV / 2P PV-10, After-Tax | 0.75x | 0.73x – 0.76x(2) | 0.75x |
Strategic Rationale
Benefits for Both Strathcona and Greenfire
- Unification of Two Complementary Businesses with Parallel Growth Plans – The Transaction will bring together two long-life oil sands and heavy oil companies, better positioned to execute each company's growth plans. Over the next five years Strathcona and Greenfire each plan to grow production at an 11-12% CAGR through a combination of drilling to fill existing facilities and brownfield expansions. Beyond 2031, both companies also have attractive brownfield and greenfield growth opportunities across prospective areas such as Plover Lake, Taiga, Glenbogie, Selina, Muriel Lake, Corner, and Chard. The improved access to capital of the combined business is expected to allow the acceleration of each of these standalone plans.
- Expanded SAGD Scale and Expertise – The combined business will have over 3.0 billion barrels of proved plus probable ("2P") oil reserves, equating to a 2P reserves life index of 54 years, the longest of any publicly traded company in Canada (by approximately 20 years) upon closing. The combined business will be the 4th largest SAGD operator in Canada and the only company with significant operations across all three major oil sands deposits (Athabasca, Cold Lake and Lloydminster) and all major producing formations (the McMurray, Clearwater and Mannville). Strathcona expects the combined business to benefit from shared learnings and best practices across business units, driving improved operational performance.
- Unique Market Position – The combined business will be the only publicly traded oil sands company with current oil sands production between 25 and 450 Mbbls / d, offering a more rapid growth profile than larger oil sands operators and a better capitalized, lower risk asset base than smaller oil sands operators. Strathcona will be the only oil sands operator without natural gas or downstream operations, providing investors the only long-life oil "pure play".
Benefits for Strathcona
- Meaningful Synergies and Extended Tax Horizon: Strathcona expects to realize approximately $75 million of annual run-rate synergies within the first year of combined operations, due to a combination of lower borrowing costs, procurement efficiencies, and the removal of duplicative public company costs. In addition, Greenfire's $2.8 billion of tax pools ($2.0 billion of which are immediately deductible) are expected to allow Strathcona to extend its cash tax horizon from 2027 to 2031 at US$75 / bbl WTI, resulting in approximately $400 million of expected cash tax savings over the next four years.
- Accelerates Path to Investment Grade Credit Rating: Strathcona expects the combined business will have the necessary size and scale to earn an investment grade credit rating in the Canadian bond market within one year of closing, lowering Strathcona's cost of borrowing, reducing midstream costs, and increasing its financial flexibility.
- Immediately Accretive to Net Asset Value and Free Cash Flow: The Transaction is expected to be approximately 6% accretive to Strathcona's YE 2025 proved plus probable net asset value, after-tax per share ("2P NAV"), including synergies, and immediately accretive to free cash flow after sustaining capital.
Benefits for Greenfire
- Option for Continued Participation in Strathcona on Accretive Basis: The GFR Share Option share exchange ratio is directly in-line with the relative standalone 2P NAV of Strathcona and Greenfire. Inclusive of synergies, the GFR Share Option is expected to be immediately accretive to free cash flow after sustaining capital and approximately 3% accretive relative to Greenfire's standalone 2P NAV.
- Participation in Lower Risk, Scaled Business: The GFR Share Option provides Greenfire shareholders with the opportunity to participate in a larger, diversified business instead of a single-asset company, reducing single-event risk while increasing access to capital to accelerate organic growth.
- Option for Immediate Attractive Cash Premium: The GFR Cash Option provides an attractive premium for Greenfire shareholders who are not looking for continued participation, reflective of the unique value and synergy opportunities Greenfire is contributing to Strathcona.
Process and Approvals
In considering the Transaction, the boards of directors of Strathcona and Greenfire each established a special committee composed of directors independent from WEF and management (the "Strathcona Special Committee" and the "Greenfire Special Committee", respectively) to consider, evaluate and oversee negotiations with respect to the Transaction and make a recommendation to its respective board with respect thereto. The Strathcona Special Committee engaged Jefferies Securities, Inc. ("Jefferies") as its financial advisor and Torys LLP as its legal advisor. The Greenfire Special Committee engaged CIBC Capital Markets ("CIBC") as its financial advisor and Norton Rose Fulbright Canada LLP as its legal advisor.
In connection with the Transaction, the Strathcona Special Committee supervised the preparation of and considered a formal valuation of Greenfire shares by Jefferies in accordance with Multilateral Instrument 61-101 – Protection of Minority Security Holders in Special Transactions ("MI 61-101") and received Jefferies' opinion as to the fairness, from a financial point of view, to Strathcona of the consideration to be paid by Strathcona pursuant to the Transaction, in each case as of November 8, 2026, and based on and subject to various assumptions, qualifications, limitations and other matters (the "Jefferies Valuation and Opinion"). In connection with the Transaction, the Greenfire Special Committee supervised the preparation of and considered CIBC's formal valuation of Greenfire's and Strathcona's shares prepared in accordance with MI 61-101 and received CIBC's opinion that the consideration to be received by the non-WEF Greenfire Shareholders pursuant to the Arrangement Agreement was fair, from a financial point of view, to non-WEF Greenfire shareholders, in each case as of November 8, 2026, and based on and subject to various assumptions, qualifications, limitations and other matters (the "CIBC Valuation and Opinion"). Neither the formal valuations nor opinions of Jefferies or CIBC constitute a recommendation as to how to vote or act in connection with the Transaction or any other matter.
The Strathcona Special Committee evaluated the Transaction with the assistance of management and legal and financial advisors and has unanimously determined, and the Strathcona board of directors (with interested directors abstaining), based on the unanimous recommendation of the Strathcona Special Committee, has determined, that the Transaction is in the best interests of Strathcona and is fair to non-WEF Strathcona shareholders. The Greenfire Special Committee evaluated the Transaction with the assistance of management and legal and financial advisors and has unanimously determined, and the Greenfire board of directors (with interested directors abstaining), based on the unanimous recommendation of the Greenfire Special Committee, has determined, that the Transaction is in the best interests of Greenfire and is fair to non-WEF Greenfire shareholders.
The Arrangement Agreement includes customary deal protection provisions, including that each party has agreed not to solicit or initiate any discussions regarding any other transaction, subject to customary "fiduciary out" rights to respond to a superior proposal. Strathcona and Greenfire have also granted each other a right to match any superior proposal and each has agreed to pay a termination fee to the other party if the Arrangement Agreement is terminated in certain circumstances.
The Transaction is to be effected by way of a plan of arrangement under the Business Corporations Act (Alberta) (the "Arrangement"). A joint information circular for the special meetings of shareholders of Strathcona and Greenfire to consider the Transaction is expected to be mailed in late November 2026 and will be available on both company websites, as well as on SEDAR+. Strathcona, Greenfire and WEF will also jointly prepare and file with the U.S. Securities and Exchange Commission (the "SEC") a transaction statement on Schedule 13E-3 (the "Schedule 13E-3"). A copy of the Arrangement Agreement will also be available on SEDAR+ and, in the case of Greenfire, on EDGAR. All shareholders are urged to read the joint information circular once available as it will contain additional important information concerning the Transaction and the special meetings of shareholders of Strathcona and Greenfire, including the deadline for making elections to receive the GFR Cash Option or the GFR Share Option.
The Transaction is subject to approval of not less than two-thirds of the votes cast at each of the Strathcona and Greenfire shareholder meetings, and the fulfilment of other conditions that are typical for transactions of this nature, including Competition Act approval. In addition, the Transaction is subject to minority shareholder approval under MI 61-101 for both Strathcona and Greenfire, being a simple majority of votes cast at their respective shareholder meetings, excluding votes cast by WEF and other shareholders required to be excluded pursuant to MI 61-101 and, in the case of Strathcona, the TSX. In addition to shareholder approvals, the Transaction is subject to regulatory approvals, including the approval of the TSX and the approval of the Court of King's Bench of Alberta. The special meetings of the shareholders of each of Strathcona and Greenfire are expected to be held in January 2027, with closing expected shortly thereafter, provided that the required court, shareholder and regulatory approvals described above have been obtained.
Greenfire shareholders who elect the GFR Share Option will receive a dividend on closing equal to the regular quarterly dividends paid by Strathcona between today and closing, payable on a per share basis on their pro forma Strathcona shares. The dividend will be declared by Strathcona following Strathcona's acquisition of Greenfire and as part of the Transaction. Following Strathcona's acquisition of Greenfire, as part of the Transaction, Greenfire will be amalgamated into Strathcona, with the combined entity continuing as Strathcona Resources Ltd.
WEF has signed a support agreement in favour of the Transaction, committing to vote all of its Strathcona and Greenfire shares in favour of the Transaction at the relevant shareholder meetings, and to elect for the GFR Share Option for its Greenfire shares. Upon completion of the Transaction, WEF will hold between 60% and 64% of the shares of Strathcona, depending on the elections made by non-WEF Greenfire shareholders.
In addition, all non-WEF board members and executive officers of Strathcona and Greenfire, including independent directors, have signed support agreements in favour of the Transaction.
Following completion of the Transaction, it is expected that the Greenfire common shares will be delisted from the TSX and the New York Stock Exchange (the "NYSE"), and that Greenfire will cease to be a reporting issuer under Canadian securities laws in all provinces of Canada and that the Greenfire shares will be deregistered with the SEC. Strathcona does not intend to list its shares on the NYSE following the Transaction.
Early Warning Reporting
WEF has not acquired or disposed of any securities of Strathcona or Greenfire. As a result of its entry into the support agreement in favour of the Transaction, WEF will file amended early warning reports in accordance with National Instrument 62-104 – Take-Over Bids and Issuer Bids and National Instrument 62-103 – The Early Warning System and Related Take-Over Bid and Insider Reporting Issues to reflect a change in a material fact contained in its most recently filed reports. The reports will be filed electronically with the applicable securities regulatory authority in each province of Canada and will be available on SEDAR+ at www.sedarplus.ca. WEF will also file an amendment to its Schedule 13D with the SEC in respect of its holdings of Greenfire shares, which will be available on EDGAR at www.sec.gov. For further information or to obtain a copy of the early warning reports, please contact WEF's Chief Executive Officer at 403-930-6048 or info@waterous.com. The head office of WEF is located at 600, 301 – 8th Avenue SW, Calgary, Alberta T2P 1C5.
Important Additional Information and Where to Find It
In connection with the Transaction, Strathcona and Greenfire intend to file relevant materials on SEDAR+ and, for Greenfire, with the SEC on EDGAR, including the Schedule 13E-3. Shareholders will be able to obtain these documents, as well as other filings containing information about Strathcona, Greenfire, the Transaction and related matters, without charge, from the SEDAR+ website at www.sedarplus.ca and from the SEC's website at www.sec.gov.
Advisors
Jefferies served as financial advisor and Torys LLP as legal advisor to the Strathcona Special Committee.
CIBC Capital Markets served as financial advisor and Norton Rose Fulbright Canada LLP as legal advisor to the Greenfire Special Committee.
J.P. Morgan served as financial advisor and Blake, Cassels & Graydon LLP and Skadden, Arps, Slate, Meagher & Flom LLP as legal advisors to Strathcona.
RBC Capital Markets served as financial advisor and Bennett Jones LLP and Scale LLP as legal advisors to Greenfire.
About Strathcona
Strathcona is one of North America's fastest growing pure play heavy oil producers with operations focused on thermal oil and enhanced oil recovery. Strathcona is built on an innovative approach to growth achieved through the consolidation and development of long-life assets. Strathcona's common shares (symbol SCR) are listed on the TSX.
For more information about Strathcona, visit www.strathconaresources.com.
Investor inquiries:
info@strathconaresources.com
Media inquiries:
communications@strathconaresources.com
About Greenfire
Greenfire is an oil sands producer actively developing its long-life and low-decline thermal oil assets in the Athabasca region of Alberta, Canada, with its registered office in Calgary, Alberta. Greenfire plans to leverage its large resource base and significant infrastructure in place to drive meaningful, capital-efficient production growth. Greenfire common shares are listed on the New York Stock Exchange and the Toronto Stock Exchange under the trading symbol "GFR".
For more information, visit www.greenfireres.com.
Investor inquiries:
investors@greenfireres.com
Notes
All amounts in this press release are stated in Canadian dollars unless otherwise specified.
(1) A non-GAAP financial measure which does not have a standardized meaning under IFRS® Accounting Standards; see "Non-GAAP Financial Measures" section of this press release.
(2) Metrics reflect Greenfire TEV and pro forma Strathcona share count inclusive of WEF electing GFR Share Option.
(3) Pro forma for Connacher acquisition.
(4) Share prices are based on closing prices on November 6, 2026, with the Greenfire share price and market capitalization shown as a range reflecting the implied value of the GFR Share Option and the GFR Cash Option. Ranges for the pro forma combined business reflect the range of potential elections by non-WEF Greenfire shareholders. Shares outstanding and net Debt are as at September 30, 2026. Pro forma figures represent the arithmetic sum of each company's standalone figures (adjusted, where applicable, for the issuance of Strathcona shares and payment of cash consideration under the Transaction) and do not reflect any synergies or pro forma accounting and management adjustments. See "Notes", "Non-GAAP Financial Measures" and "Oil and Gas Advisory" below. Figures may not sum due to rounding.
Advisories
Non-GAAP Financial Measures
Certain financial measures in this press release are non-GAAP financial measures. Non-GAAP financial measures are used internally by management of each of Strathcona and Greenfire to assess performance, and also provide investors with meaningful metrics to assess each company's performance compared to other companies in the same industry. These measures do not have a standardized meaning under IFRS Accounting Standards and therefore may not be comparable to similar measures presented by other companies. Investors are cautioned that these measures should not be considered in isolation or construed as an alternative to financial measures determined in accordance with generally accepted accounting principles ("GAAP"), and should not be considered more meaningful than GAAP measures in evaluating either company's performance.
"Net Debt" is used by management to analyze leverage and liquidity. Net Debt is calculated as debt less cash and cash equivalents, cross-currency swap assets / (liabilities), and Greenfire's infrastructure loan. The most directly comparable GAAP measure to Net Debt is debt. The following table is a reconciliation of Net Debt to debt for each of Strathcona, Greenfire and the combined business as at September 30, 2026:
(C$ millions) | Strathcona | Greenfire | Combined |
Debt | 1,736 | 604 | 2,340 |
Less: Cash and cash equivalents | - | (9) | (9) |
Less: Cross-currency swap asset | (25) | - | (25) |
Less: Infrastructure loan | - | (46) | (46) |
Net Debt | 1,711 | 549 | 2,260 |
Oil and Gas Advisory
Unless indicated otherwise, production volumes and per-unit statistics are presented throughout this press release on a "gross" basis as determined in accordance with National Instrument 51-101 – Standards for Disclosure for Oil and Gas Activities ("NI 51-101"), which is each company's gross working interest basis before deduction of royalties and without including any royalty interests of such company. This press release makes assumptions relating to future production volumes based on reserve evaluation calculations prepared by third-party independent evaluators. Statements relating to reserves are deemed to be forward-looking statements as they involve the implied assessment, based on certain estimates and assumptions, that the reserves described can be profitably produced in the future. There are numerous uncertainties inherent in estimating quantities of 2P reserves and in projecting future rates of production. The total amount or timing of actual future production may vary significantly from reserves and production estimates. Uncertainties and risk factors are described in Strathcona's Annual Information Form dated March 11, 2026 (the "Strathcona AIF") and Greenfire's Annual Information Form dated March 12, 2026 (the "Greenfire AIF"), and from time to time in each company's public disclosure documents, which are available on the respective company's SEDAR+ profile at www.sedarplus.ca and, in the case of Greenfire, in its annual report on Form 40-F filed with the SEC, which is available on Greenfire's EDGAR profile at www.sec.gov.
Reserves estimates of Strathcona are based on the evaluations of McDaniel & Associates Consultants Ltd. ("McDaniel"), independent reserves evaluator for Strathcona, as of December 31, 2025 and in accordance with the Canadian Oil and Gas Evaluation Handbook (the "COGE Handbook"), and contained in the independent engineering evaluation of Strathcona's petroleum and natural gas reserves prepared by McDaniel effective December 31, 2025 (the "Strathcona Report") and presented in accordance with NI 51-101 in the Strathcona AIF. Reserves estimates of Greenfire are based on: (a) the evaluations of McDaniel, independent reserves evaluator for Greenfire, as of December 31, 2025 and in accordance with the COGE Handbook, and contained in the independent engineering evaluation of Greenfire's bitumen reserves in its Hangingstone facilities prepared by McDaniel effective December 31, 2025 (the "Greenfire Report") and presented in accordance with NI 51-101 in the Greenfire AIF; and (b) the evaluations of GLJ Ltd. ("GLJ"), independent reserves evaluator for Connacher Oil and Gas Limited ("Connacher"), as of December 31, 2025 and in accordance with the COGE Handbook, and contained in the independent engineering evaluation of all of Connacher's oil, natural gas liquids and natural gas interests prepared by GLJ dated March 31, 2026, with an effective date of December 31, 2025 (the "Connacher Report"). References to reserves of Greenfire represent the arithmetic sum of the reserves estimates of Greenfire and Connacher on a standalone basis, and references to pro forma or combined production and reserves of Strathcona and Greenfire represent the arithmetic sum of each company's respective production volumes and reserves estimates on a standalone basis, and in each case do not account for any potential synergies or adjustments that may result from Greenfire's acquisition of Connacher or the Transaction, as applicable, except for pro forma taxes based on the combined company's tax pools. In addition, adjustments arising from differences among the Strathcona Report, the Greenfire Report and the Connacher Report, such as differences in the professional judgments underlying the reserves estimates, level of development, capital requirements, operating costs and other relevant considerations, may adversely affect the pro forma addition of reserves.
Reserves information in respect of Connacher has been obtained from Connacher and has not been independently verified. While Greenfire does not have any knowledge that such information may not be accurate, there can be no assurance that such information is complete or accurate. Greenfire makes no representation or warranty, expressed or implied, as to the accuracy or completeness of such information.
This press release contains certain oil and gas metrics, such as "reserves life index", "PV-10" and "TEV / bbls / d", which do not have standardized meanings or standard methods of calculation and therefore such measures may not be comparable to similar measures used by other companies and should not be used to make comparisons. Such metrics have been included herein to provide readers with additional measures to evaluate the Transaction; however, such measures are not reliable indicators of future performance and future performance may not compare to performance in previous periods and therefore such metrics should not be unduly relied upon. Reserves life index is calculated by dividing total gross 2P reserves by annualized YTD 2026 production. "PV-10" reflects the applicable independent reserves evaluator's estimated after-tax net present value of future net revenue attributable to 2P reserves, discounted at 10%, as at December 31, 2025, excluding synergies. "TEV / bbls / d" is calculated by dividing total enterprise value by production for a given time period.
References to "oil" in this press release include bitumen and heavy oil. References to "Mbbls / d" mean thousands of barrels per day and "MMbbls" means millions of barrels. References to "SAGD" mean steam-assisted gravity drainage.
Forward-Looking Information
This press release contains forward-looking information and forward-looking statements (collectively, "forward-looking information") within the meaning of applicable securities laws. The forward-looking information in this press release is based on the current internal expectations, estimates, projections, assumptions and beliefs of Strathcona and Greenfire. Such forward-looking information is not a guarantee of future performance and involves known and unknown risks, uncertainties and other factors that may cause actual results or events to differ materially from those anticipated in such forward-looking information. Strathcona and Greenfire believe the material factors, expectations and assumptions reflected in the forward-looking information are reasonable as of the time of such information, but no assurance can be given that these factors, expectations and assumptions will prove to be correct, and such forward-looking information should not be unduly relied upon. The use of any of the words "expect", "target", "anticipate", "intend", "estimate", "objective", "ongoing", "may", "will", "project", "plan", "believe", "depends", "could" and similar expressions is intended to identify forward-looking information.
In particular, but without limiting the generality of the foregoing, this press release contains forward-looking information pertaining to the following: the Transaction and the terms thereof, including the anticipated total transaction value of the Transaction; the GFR Share Option and the GFR Cash Option, and the premiums represented thereby; the absence of proration; the entitlement of Greenfire shareholders who elect the GFR Share Option to receive a dividend payment on closing; the expected number of Strathcona shares to be issued and the amount of cash consideration to be paid under the Transaction; WEF's commitment to vote in favour of the Transaction and to elect the GFR Share Option; the expected ownership of Strathcona by former Greenfire shareholders and WEF following completion of the Transaction; expected sources of funding of the Transaction; the expected amalgamation of Greenfire into Strathcona; the continuation of Strathcona's board of directors and executive officers; the senior management of Greenfire leading day-to-day operations of Greenfire's assets within SCR Central Athabasca, Colin Germaniuk serving as President of SCR Central Athabasca, and SCR Central Athabasca functioning semi-autonomously within Strathcona, following completion of the Transaction; the governance structure of SCR Central Athabasca within Strathcona; the pro forma capitalization, total enterprise value, production and reserves of the combined business; benefits of the Transaction for both Strathcona and Greenfire; Strathcona's and Greenfire's planned standalone production growth at an 11-12% CAGR over the next five years, their growth opportunities beyond 2031, and the combined business's expected improved access to capital and ability to accelerate such plans; expected 2031 production; the combined business's expected 2P reserves, reserves life index, SAGD scale and market position; the expected benefits of shared learnings and best practices across business units; the combined company's rapid growth profile and lower risk asset base; the anticipated approximately $75 million per year of run-rate synergies within the first year of combined operations and the sources thereof; the expectation that the deduction of Greenfire's tax pools will allow Strathcona to extend its cash tax horizon from 2027 to 2031 and result in approximately $400 million of cash tax savings over the next four years; the expectation that the combined business will earn an investment grade credit rating in the Canadian bond market within one year of closing and the benefits thereof, including lower borrowing costs, reduced midstream costs and increased financial flexibility; the expected accretion of the Transaction to Strathcona's 2P NAV and free cash flow, and of the GFR Share Option to Greenfire shareholders relative to Greenfire's standalone 2P NAV and free cash flow; the expected benefits of the GFR Share Option and the GFR Cash Option to Greenfire shareholders, including improved trading liquidity, a more diversified shareholder base and future Strathcona dividends; the receipt of required shareholder, court, TSX and Competition Act approvals and the satisfaction of other closing conditions; the expected timing of filing and mailing the joint information circular, filing the Schedule 13E-3, holding the special meetings of shareholders and closing the Transaction; the filing by WEF of amended early warning reports and an amendment to its Schedule 13D; the expected delisting of the Greenfire shares from the TSX and the NYSE, Greenfire ceasing to be a reporting issuer in Canada and the deregistration of the Greenfire shares with the SEC; the payment of a termination fee in certain circumstances; and Strathcona's intention not to list its shares on the NYSE.
All forward-looking information reflects the beliefs and assumptions of Strathcona and Greenfire based on information available at the time the applicable forward-looking information is disclosed and in light of current expectations with respect to such matters as: the completion of the Transaction on anticipated terms and timing, or at all; the receipt of required approvals and the timing thereof; the elections made by Greenfire shareholders; the availability of borrowings under Strathcona's existing reserves-based credit facility to fund the GFR Cash Option and other cash consideration payable under the Arrangement; the ability to integrate Greenfire's business and operations and realize the anticipated strategic, operational and financial benefits and synergies of the Transaction on anticipated timelines; that there will be no material change to either company's operations prior to completion of the Transaction; the outlook for general economic trends, industry trends, prevailing and future commodity prices, foreign exchange rates and interest rates; prevailing and future royalty regimes and tax laws; the deductibility of Greenfire's tax pools; Strathcona's ability to declare and pay dividends; expectations regarding differentials and realized prices; future production rates and reserves volumes; the impact of inflation; the integrity and reliability of each company's assets; decommissioning obligations; the ability to comply with financial covenants; credit rating agency assessments; and the ability to comply with applicable regulations, including those related to emissions.
Actual results or events may differ materially from those anticipated in the forward-looking information as a result of risks including, without limitation: not completing the Transaction on anticipated terms and timing, or at all, including the failure to obtain required approvals or satisfy other closing conditions; the unavailability of borrowings under Strathcona's reserves-based credit facility to fund the GFR Cash Option and other cash consideration payable under the Arrangement; the payment of a termination fee if the Transaction is not completed in certain circumstances; the delay or inability to integrate Strathcona's and Greenfire's respective businesses and realize the anticipated benefits and synergies of the Transaction; potential adverse reactions or changes to business relationships resulting from the announcement or completion of the Transaction; the consequences of not completing the Transaction, including share price volatility, negative reactions from the investment community and the payment of certain costs related to the Transaction; potential undisclosed liabilities; the accuracy of pro forma information of the combined business; the failure to obtain an investment grade credit rating; changes in tax laws or the ability to deduct tax pools; the imposition of, or changes or proposed changes to, tariffs, export or import restrictions and other trade measures, and the impact of trade disputes between Canada, the United States and other countries, including on commodity prices, differentials, market access and costs; the focus of management's time and attention on the Transaction; and other factors discussed under the "Risk Factors" sections of the Strathcona AIF and the Greenfire AIF, and from time to time in each company's public disclosure documents, which are available on the respective company's SEDAR+ profile at www.sedarplus.ca and, in the case of Greenfire, on its EDGAR profile at www.sec.gov.
The guidance in respect of expectations of future periods in this press release, including expected synergies, cash tax savings and free cash flow accretion, may be considered to be a financial outlook for the purposes of applicable securities laws. Such information is based on assumptions about future events, including economic conditions and proposed courses of action, based on management's assessment of the relevant information currently available. Actual results may differ significantly from such projections. The financial outlook contained in this press release has been approved by management of Strathcona and Greenfire as of the date of this press release, and readers are cautioned that it should not be used for purposes other than those for which it is disclosed herein.
The foregoing risks should not be construed as exhaustive. The forward-looking information contained in this press release speaks only as of the date of this press release, and neither Strathcona nor Greenfire assumes any obligation to publicly update or revise such forward-looking information to reflect new events or circumstances, except as may be required pursuant to applicable laws. Any forward-looking information contained herein is expressly qualified by this cautionary statement.
Certain market and industry data contained in or implied by this press release is based upon information from government or independent industry publications and reports, or based on estimates derived from such publications and reports. Such publications and reports do not guarantee the accuracy or completeness of their information. While management of Strathcona and Greenfire believe this data to be reliable, market and industry data are subject to variations and cannot be verified with complete certainty due to limits on the availability and reliability of raw data, the voluntary nature of the data gathering process and other inherent limitations and uncertainties.
 View original content to download multimedia:https://www.prnewswire.com/news-releases/strathcona-resources-ltd-announces-agreement-to-acquire-greenfire-resources-ltd-302932925.html
SOURCE Strathcona Resources Ltd.
